Ecuador’s Cocoa at the EUDR Crossroads: The Real Challenge Is Not Only Deforestation, but Proof

Ecuador’s cocoa sector has the geography, market reputation and increasingly sophisticated supply chains to remain a major supplier to Europe. But a spatial assessment by MosaiX shows that the transition toward EUDR-ready cocoa will depend on something more fundamental: knowing exactly where cocoa comes from, what happened on that land before 2021, and whether the evidence can withstand scrutiny.

Ecuador is one of the world’s important cocoa origins, with production landscapes stretching across the humid lowlands of the Pacific coast and into parts of the country’s interior. A recent geospatial assessment identified roughly 3 million hectares of potential cocoa-planted area, equivalent to about 11.9% of Ecuador’s territory, with major concentrations in Manabí, Esmeraldas, Los Ríos, Morona Santiago, Santo Domingo de los Tsáchilas and Guayas.

That scale tells only part of the story.

As the European Union Deforestation Regulation reshapes expectations around cocoa sourcing, the central question is shifting from where cocoa is grown to whether every shipment can be connected to land whose history, legality and boundaries can be demonstrated.

The assessment suggests Ecuador has considerable potential to make that transition. But it also reveals several gaps that could become far more important than production volume itself.

A land-documentation gap hiding beneath the cocoa map

One of the most striking findings concerns land status.

According to the spatial comparison used in the assessment, around 2.8 million hectares, or approximately 92% of the mapped potential cocoa area, fall outside the registered land layer used in the analysis, while roughly 244,000 hectares, or 8%, appear as registered.

That figure needs to be interpreted carefully.

The report itself notes that the cocoa dataset represents potential planting areas as well as areas identified as cocoa, meaning it can overestimate actual planted hectares. It also warns that cadastral information can be incomplete in rural areas. The 92% figure should therefore not be read as proof that 92% of Ecuadorian cocoa farms are legally invalid or without legitimate tenure. It is better understood as a measure of the documentation and spatial-data gap that would need to be resolved during due diligence.

That distinction matters.

For EUDR implementation, a farm does not become compliant simply because its coordinates are known. Buyers need sufficiently reliable evidence connecting a commodity to its production plot, alongside evidence supporting deforestation-free status and compliance with applicable laws.

In other words, mapping is the beginning of due diligence, not the end of it.

The deforestation signal is relatively small—but it cannot be ignored

When the mapped cocoa plots were overlaid with post-2020 forest-loss information, the analysis identified 185 plots out of 212,572 assessed plots, covering approximately 65.4 hectares, that intersected areas recorded as deforested during 2021–2022.

Viewed against hundreds of thousands of plots, this is not evidence that Ecuadorian cocoa as a whole is driving widespread recent deforestation.

But from a regulatory perspective, percentages can be misleading.

EUDR due diligence operates much closer to the level of individual production plots and consignments. A relatively small number of problematic farms can therefore become significant when cocoa from those farms enters an otherwise compliant supply chain.

The implication is important: national-level deforestation statistics alone cannot determine whether a cocoa shipment is compliant.

The question eventually becomes much more specific:

Was this cocoa produced on this plot, and was that plot forest-free after the EUDR cutoff?

A rapidly changing forest-risk context

The broader forest landscape also deserves attention.

Using the European Commission Joint Research Centre’s Tropical Moist Forest dataset, the assessment found national forest loss increasing from approximately 4,913 hectares in 2021 to 12,232 hectares in 2022, falling slightly to around 11,013 hectares in 2023, then rising sharply to approximately 45,367 hectares in 2024.

The spatial pattern is equally important. Forest loss is not distributed uniformly across Ecuador. The report identifies Esmeraldas as the province with the highest cumulative deforestation among the provinces examined, suggesting that due diligence cannot rely on one uniform monitoring strategy across the country.

A cocoa plot in a stable agricultural landscape and another close to an active forest-conversion frontier may both need geolocation and documentation, but they do not necessarily require the same level of monitoring.

That points toward a more practical approach to EUDR implementation: risk-based verification rather than treating every cocoa farm identically.

Protected forests reveal a second kind of risk

Deforestation is only one part of the picture.

The assessment also compared cocoa plots against Ecuador’s mapped Permanent Forest Reserves. Around 2.19 million hectares are represented in the reserve dataset used by the study, and the overlay identified 184 cocoa plots covering approximately 527 hectares that intersect these reserve areas.

This finding illustrates an often-overlooked aspect of commodity compliance.

A plantation may show no recent forest clearance and still raise a due-diligence concern if it occupies land where agricultural production conflicts with applicable land-use restrictions.

For companies building EUDR systems, satellite deforestation monitoring is therefore not enough. Plot screening increasingly needs to combine several layers: land cover, forest-loss history, cadastral information, protected areas and other relevant legal boundaries.

The challenge becomes less about producing a single map and more about assembling an evidence stack around every production location.

What plot-level evidence looks like in practice

A case study from Agrícola del Litoral in Los Ríos Province offers a useful illustration.

Three parcels covering approximately 243.6 hectares were evaluated using cadastral information, protected-area data and satellite imagery. Planet imagery from September 2019 and May 2025 indicated that the parcels were already in agricultural use before the EUDR cutoff and remained agricultural afterwards. The nearest mapped forest reserve was approximately 27 kilometres away, with no overlap identified in the available dataset.

The significance of the example is not the individual farm.

It is the method.

Instead of asking a supplier simply to declare that its cocoa is deforestation-free, the process builds a reproducible file containing parcel boundaries, historical imagery, land-status information and protected-area screening.

That is much closer to what credible commodity due diligence increasingly requires: evidence that another analyst, buyer or auditor can reproduce.

From cocoa mapping to an evidence system

This is where many traceability programs encounter their real bottleneck.

Companies may already possess farmer lists, GPS points, certification records or sourcing contracts. But those datasets are often stored separately. Plot identifiers change between systems. Polygons may contain errors. Legal documents are held offline. Satellite assessments may not be linked back to specific suppliers or shipments.

The report proposes a workflow starting with a stable plot registry, followed by geolocation quality assurance, deforestation and reserve screening, legality documentation, risk classification, evidence archiving and continuous monitoring.

This represents an important shift in thinking.

Traceability should not simply answer “Who is the farmer?”

It should eventually answer:

Which plot produced the cocoa, what is the land history of that plot, what legal evidence supports production there, what risks were detected, what mitigation was undertaken, and which shipment contains the resulting cocoa?

Digital systems can make that process scalable. The report describes the use of integrated geolocation, automated forest-loss screening, protected-area and cadastral overlays, supply-chain connections and standardized reporting as components of an EUDR-oriented due-diligence architecture.

Technology, however, cannot fix unreliable source data by itself. The report explicitly notes that field mapping, farmer engagement and clear rules over data ownership and editing remain essential foundations.

The opportunity for Ecuador

Perhaps the most important conclusion from the assessment is that Ecuador’s cocoa challenge should not be framed simply as a deforestation problem.

The analysis does identify post-2020 forest-loss overlaps and cocoa plots intersecting protected forest areas. Those cases deserve investigation.

But the larger structural challenge is turning fragmented spatial, cadastral and supply-chain information into verifiable plot-level evidence.

That is also where the opportunity lies.

Ecuador already has national agricultural datasets, environmental information, a strong export-oriented cocoa sector and increasingly sophisticated private traceability initiatives. The next step is connecting these pieces.

For exporters and buyers, this means improving polygon quality, validating supplier locations, screening historical land-use change and building stronger links between farm data and physical cocoa flows.

For government agencies, it means improving interoperability among agricultural, cadastral and environmental datasets.

And for smallholders, it means ensuring that the transition toward stricter documentation does not simply exclude producers whose land tenure is legitimate but poorly represented in formal digital systems.

The report’s broader conclusion captures the moment well: Ecuador combines strong cocoa-market opportunities with remaining gaps around land tenure information and isolated instances of cocoa associated with recently cleared or protected land.

The future of EUDR-ready cocoa may therefore depend less on producing another sustainability declaration and more on something much more concrete:

building a chain of evidence—from the cocoa tree, to the plot, to the supplier, to the shipment.

And in an increasingly regulated commodity market, that evidence may become as valuable as the cocoa itself.
From RSPO Mill List Disclosure to EUDR Readiness: Closing a Transparency Gap in Europe’s Palm Oil Supply Chains

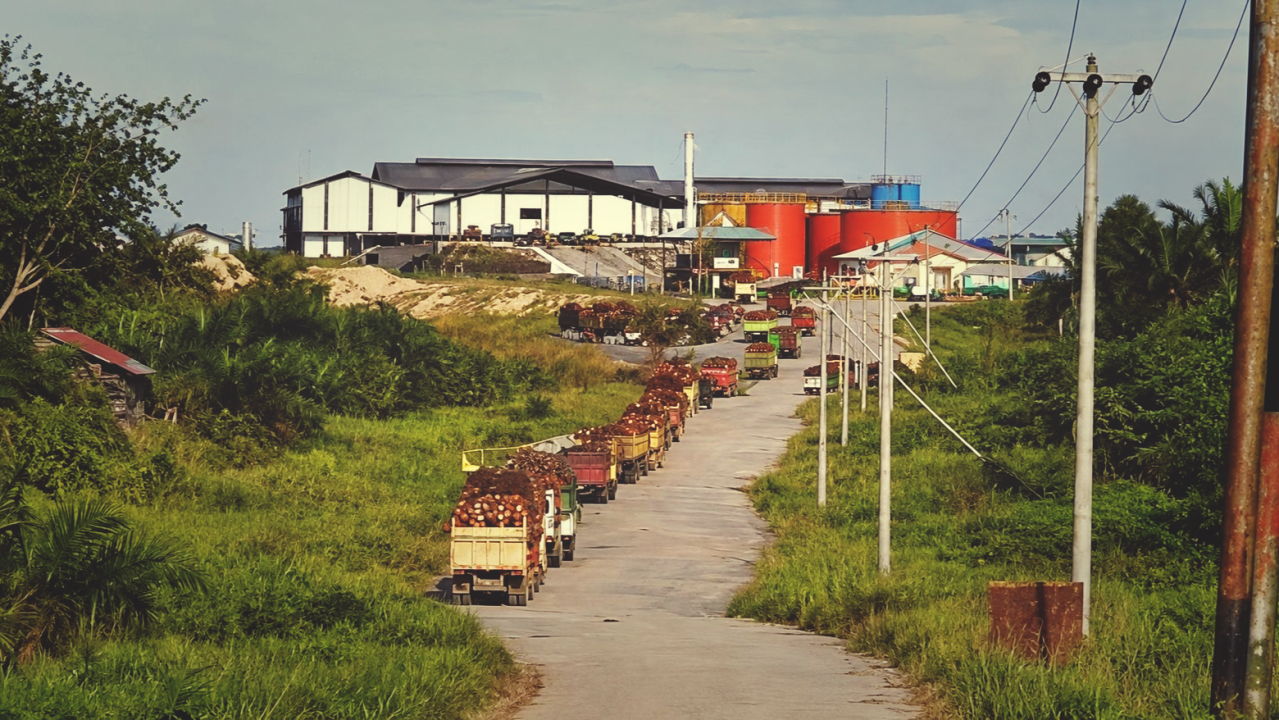
A palm oil mill can seem very far from a supermarket shelf in Europe. In reality, it is one of the most important links connecting tropical production landscapes with the companies, products and consumers at the other end of the global supply chain.

A bottle of shampoo in Amsterdam, a biscuit in Berlin, or an industrial ingredient arriving at the Port of Rotterdam may have traveled through a chain that began thousands of kilometers away, among oil palm plantations in Indonesia or Malaysia. Fresh fruit bunches are harvested and delivered to a palm oil mill, where they are processed into crude palm oil or palm kernel products. From there, the oil may pass through refiners, crushers, traders, ports, manufacturers, and distributors before appearing in food, cosmetics, oleochemicals, animal feed, household products, or energy markets. By the time it reaches Europe, its physical journey can be long, but its information trail can be even more complicated.

For more than two decades, the palm oil industry has been trying to make that journey more visible. One of the most influential efforts began in 2004 with the creation of the Roundtable on Sustainable Palm Oil, or RSPO, a global non-profit, voluntary membership organization founded by stakeholders including WWF, the Malaysian Palm Oil Association, Unilever, Migros, and AAK. Rather than representing a single part of the industry, RSPO brought growers, processors, and traders, consumer-goods manufacturers, retailers, financial institutions, and civil-society organizations around the same table. Its ambition was to build a global framework under which palm oil could be produced and traded while reducing environmental and social harm.

Over time, that ambition evolved into standards that reach far beyond a simple certification label. The RSPO Principles and Criteria address how plantations are developed and managed, how forests and areas of high conservation and carbon value are protected, how workers and local communities are treated, and how companies demonstrate responsible production. The current 2024 Principles and Criteria, now at Version 4.2, retain safeguards addressing deforestation and incorporate approaches such as High Conservation Value and High Carbon Stock assessments, alongside stronger attention to human-rights due diligence. RSPO has prohibited conversion of primary forests since its early standards and has applied broader no-deforestation requirements based on HCV and HCS approaches since November 2018.

Certification, however, is only one part of the sustainability architecture that has developed around palm oil. During the past decade, many companies have also adopted NDPE — No Deforestation, No Development on Peat, and No Exploitation — commitments. The concept is straightforward in words but demanding in practice. Forests should not be cleared for new commodity production; new plantations should not be established on peat; and workers, indigenous peoples, local communities, and smallholders should not be exploited. Implementing these commitments has required companies to understand not only who they buy from, but what is happening within their suppliers’ production landscapes. Tools such as HCV and HCS assessments, satellite monitoring, grievance systems, supplier engagement, and the NDPE Implementation Reporting Framework have emerged to translate corporate commitments into something that can be monitored across complex supply bases.

This is where a seemingly modest piece of information becomes surprisingly important: the mill list.

A palm oil mill sits at a strategic point in the supply chain. It receives fruit from plantations and smallholders across a surrounding sourcing area, then passes processed palm products onward to refineries and traders. Knowing which mills supply a company does not tell us everything about where its palm oil originated, but it provides a crucial first map of the upstream supply chain. Without that map, tracing thousands of tonnes of palm-derived products back toward plantations becomes far more difficult.

RSPO recognized this gap before today’s regulatory debate over deforestation traceability had fully emerged. At its 15th General Assembly in 2018, RSPO members adopted Resolution GA15-6b, establishing the expectation that supplying mill lists should be made publicly available. The requirement covers both RSPO-certified and non-certified supplying mills. RSPO later created the Mill List functionality within MyRSPO, allowing companies to submit a file or a public URL and making the information visible through their membership profiles. RSPO currently asks members to submit mill lists for each half-year reporting period.

Importantly, this expectation does not stop with companies that purchase crude palm oil directly from mills. RSPO’s guidance makes clear that transparency is also expected from downstream actors such as traders, manufacturers, and retailers. A company buying refined palm oil or a palm-derived ingredient may never have a commercial relationship with an individual mill, yet it is still expected to work through its suppliers to identify the mills behind the material it buys. RSPO guidance identifies information such as the mill name, country, GPS coordinates, and parent company as part of that transparency chain. Even Supply Chain Associates and companies purchasing relatively small volumes fall within the mill-list transparency expectation.

That makes the current picture in Europe striking.

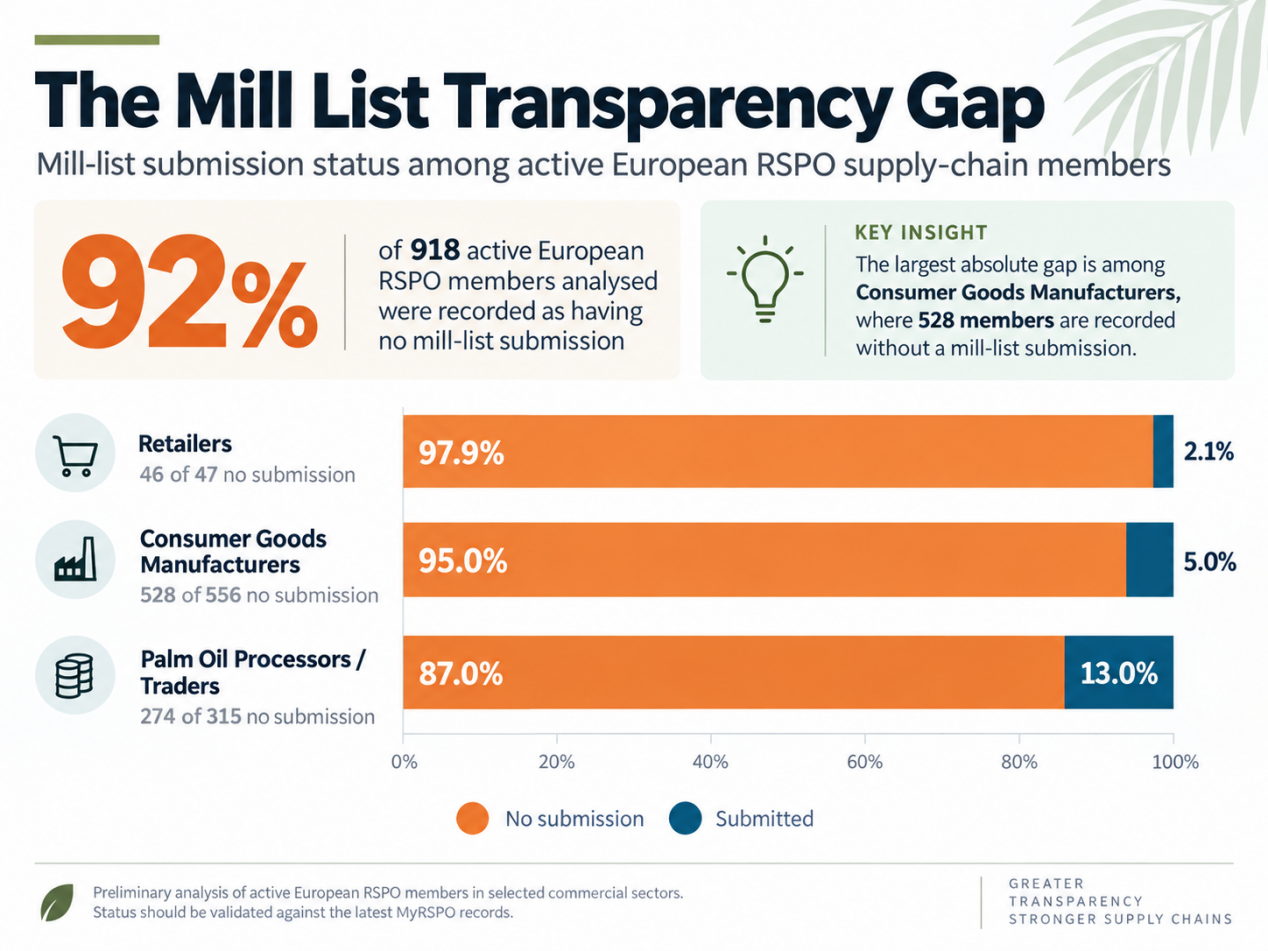
An analysis by MosaiX and Inovasi Digital of the available RSPO ACOP membership dataset examined 918 active European members across three commercially significant groups: palm oil processors and traders, consumer-goods manufacturers, and retailers. Of those companies, 848—approximately 92 percent—were recorded as having “No Submission” for their mill list in the dataset analyzed. Among processors and traders alone, 274 of 315 active European members were recorded without a submission.

The figures require caution. They represent a snapshot of the dataset rather than a formal determination of compliance, and individual records should be checked against the most recent information held by RSPO. “No Submission” can also reflect differences in reporting periods, updates, or administrative circumstances. The analysis should therefore be read as an indication of a possible transparency gap rather than a judgment on individual companies.

Even with that qualification, however, the scale of the apparent gap raises an important question. If European companies struggle to identify the mills behind their palm oil today, how easily can they make the much deeper journey toward the plantation tomorrow?

That question has become more urgent because Europe’s regulatory landscape has changed dramatically since RSPO adopted its mill-list resolution in 2018. Under the EU Deforestation Regulation, or EUDR, oil palm is one of the commodities covered by a new system of mandatory due diligence. Relevant products entering or leaving the EU market must meet deforestation-free and legality requirements. The regulation uses 31 December 2020 as its deforestation cut-off date and introduces geographic traceability to the land where covered commodities were produced. For plots larger than four hectares for relevant commodities other than cattle, the regulation’s geolocation definition provides for polygons describing the perimeter of the production plot.

Following amendments to the regulation, the main obligations are scheduled to apply to large and medium-sized operators from 30 December 2026, while most micro and small operators follow from 30 June 2027. That places European palm-oil supply chains at an unusual moment: a transparency principle developed largely through voluntary sustainability initiatives is now meeting a regulatory system built around evidence, geolocation, and due diligence.

RSPO certification and EUDR should not be confused. Neither RSPO membership nor a published mill list automatically proves EUDR compliance. The European Commission’s guidance is explicit that certification systems may support risk assessment and information gathering, but operators remain responsible for ensuring that the full requirements of the regulation are met. Among other things, EUDR traceability reaches beyond mills to the plots of land where the commodity was produced. Supply-chain models that allow material of known and unknown origin to be mixed cannot simply substitute for the traceability information required under the regulation.

Yet the two systems increasingly intersect. A credible mill list can form a bridge between a company’s commercial purchasing records and the landscapes from which its palm oil originates. Once mills are identified, supplier relationships can be organized around them. Mill identities and coordinates can be checked. Parent-company ownership can be established. Sourcing areas can begin to be mapped. Plantation polygons and smallholder origins can then be connected progressively to the mill. Satellite monitoring can be applied to those production areas, while deforestation, peat, fire, legality, and social risks can be assessed more systematically.

In this way, the mill list stops looking like an administrative spreadsheet and begins to resemble something more important: the first layer of supply-chain infrastructure.

That infrastructure also connects several generations of sustainable palm oil practices. RSPO provides certification, standards, and a multistakeholder framework. NDPE commitments extend corporate responsibility across deforestation, peat, and exploitation risks. HCV and HCS approaches help distinguish areas that should be protected. Supply-chain certification and systems such as PalmTrace help follow certified material through processing and trade. Satellite monitoring increasingly makes it possible to observe land-use change from space. Grievance and supplier-engagement processes create mechanisms for responding when problems are identified. Smallholder programs seek to ensure that increasingly sophisticated traceability systems do not simply exclude farmers who lack technology or documentation. Together, these measures reflect an industry that is gradually moving from asking whether palm oil is “sustainable” toward asking whether its environmental and social claims can actually be demonstrated.

The EUDR accelerates that evolution. It brings a regulatory demand for traceability into a sector that has already spent years building voluntary systems for certification, transparency, and responsible sourcing. Rather than treating RSPO, NDPE, and EUDR as competing frameworks, there is an opportunity to see them as different layers of the same journey. Certification establishes production and supply-chain standards. NDPE adds broader expectations for companies and suppliers. Regulation creates legally defined market requirements. The common currency among all three is increasingly credible data about origin.

This is also why the apparent European mill-list gap should not be viewed only as a problem of reporting. For some downstream companies, identifying mills is genuinely difficult. A European manufacturer may purchase an emulsifier or a specialty ingredient rather than crude palm oil. Its immediate supplier may purchase from another manufacturer, which in turn buys from several refiners. One refinery can receive material linked to many mills, and mill names themselves may appear differently across datasets because of abbreviations, subsidiaries, acquisitions, or ownership changes. Coordinates can be missing or inaccurate. The same mill can appear several times under slightly different names. A list assembled from multiple suppliers can rapidly grow into hundreds or even thousands of records.

These are not reasons to abandon transparency. They are reasons to make it easier.

There is an opportunity for RSPO and its members to treat the gap as a collective implementation challenge. Rather than simply reminding companies that mill lists are expected, a collaborative support mechanism could help downstream members turn fragmented supplier information into reliable, standardised, and regularly updated datasets. Mill identities could be matched against reference databases, coordinates validated, duplicate facilities resolved, and parent-company relationships checked. Where suppliers cannot immediately provide complete information, engagement could focus on progressively improving traceability rather than creating a simple pass-or-fail exercise.

Such support could also create a natural pathway beyond the mill. Once a company has a reliable picture of its supplying mills, the same information architecture can support plantation mapping, EUDR geolocation requirements, deforestation screening, NDPE monitoring, monitoring and wider climate and nature risk assessments. What begins as fulfilling an existing RSPO transparency commitment can therefore become a practical entry point into much more sophisticated responsible-sourcing systems.

This is where organisations operating on both sides of the supply chain may have a useful role to play. MosaiX and Inovasi Digital combine proximity to European companies with extensive experience working with palm-oil mills, corporate groups, geospatial information and production landscapes in Southeast Asia. In a potential collaboration with RSPO, that capability could be used not to create another sustainability standard, but to help members implement an existing one more effectively — connecting supplier data held in European offices with the physical mills and landscapes from which palm oil originates.

The most useful outcome would not simply be a higher number of spreadsheets uploaded to MyRSPO. It would be a stronger information bridge running from consumer markets back toward production landscapes: from a European buyer to its supplier, from the supplier to a refinery, from the refinery to its mills, and eventually from those mills to plantations and smallholders.

Twenty years ago, much of the sustainable palm oil debate centred on whether environmental and social standards could coexist with a global commodity industry. Today, the question is increasingly about evidence. Where did this material come from? Which mill processed it? Which land produced it? Was forest cleared? Was peat converted? Were people’s rights respected? And can a company demonstrate the answers rather than simply state them?

RSPO helped place transparency at the centre of sustainable palm oil long before these questions became regulatory requirements in Europe. The apparent gap in mill-list disclosure suggests that the principle is established, but the practical work of making entire supply chains visible is far from finished.

Closing that gap could therefore mean more than improving compliance with an RSPO reporting requirement. It could provide thousands of downstream companies with the first reliable coordinates on a much longer journey — one that leads from the factory floor and supermarket shelf in Europe all the way back to the forests, farms, communities and mills where the palm oil story begins.

And in an era of EUDR, NDPE and increasingly evidence-based sustainability, knowing that journey may become as important as the commodity itself.

References

  1. RSPO — Mill List Submission.Current RSPO information on GA15-6b, mill-list requirements and submission periods. RSPO Mill List Submission
  2. RSPO — Resolution GA15-6b (2018): Requiring members involved in primary procurement to publish third-party supplying mills lists.The original resolution explains the rationale for public mill disclosure and supply-chain scrutiny. RSPO Resolution GA15-6b
  3. RSPO — Mill List Submission in MyRSPO.Explains the required information, including mill name, country, GPS coordinates and parent company, and the publication of submissions through RSPO member profiles. Mill List Submission in MyRSPO
  4. RSPO — Frequently Asked Questions on Mill List Submission.Clarifies requirements for indirect buyers, Supply Chain Associates, manufacturers and retailers, and addresses implementation and certification implications.
  5. RSPO — Guide on Mill List Submission.Provides the operational process for submitting mill lists through MyRSPO and confirms that lists may be uploaded as a file or URL.
  6. European Commission — Regulation on Deforestation-free Products.Official overview of EUDR objectives, commodities covered and current implementation dates. European Commission: EUDR
  7. European Union — Regulation (EU) 2023/1115, consolidated text.Official legal text covering due diligence, geolocation and requirements for deforestation-free commodities and products. EUR-Lex: Regulation EU 2023/1115
  8. European Commission, 13 July 2026 — Commission updates product scope and tools to support EUDR.Confirms the current application dates of 30 December 2026 and 30 June 2027 and provides updated implementation context. European Commission EUDR Update, July 2026
  9. MosaiX & Inovasi Digital preliminary analysis, September 2026.Analysis of the supplied RSPO membership dataset covering active European members, membership sectors and recorded Mill List Submission status. This should be treated as a preliminary analytical dataset rather than an official RSPO compliance determination.

The Invisible Methane Gap in Palm Oil

At a palm oil mill, the most visible signs of production are easy to recognize: trucks carrying fresh fruit bunches, steaming sterilizers, piles of fibre and shell, and tanks filling with crude palm oil. One of the industry’s important climate risks, however, is almost invisible. It rises quietly from wastewater ponds.

Palm Oil Mill Effluent, usually known as POME, contains large amounts of organic matter. When it decomposes under anaerobic conditions, particularly in conventional open ponds, it produces biogas rich in methane. Studies comparing POME treatment systems have consistently shown that capturing this gas can substantially improve the climate performance of palm oil production, while also turning a waste stream into a source of energy. Research in Indonesia and Malaysia has found environmental advantages from biogas recovery compared with conventional lagoon treatment, including avoided greenhouse-gas emissions and opportunities to produce electricity or useful heat.

This matters because methane acts much faster than carbon dioxide in warming the atmosphere, and reducing methane can therefore make a meaningful contribution to near-term climate mitigation. In palm oil, the opportunity is unusually tangible. Unlike some difficult-to-abate agricultural emissions, methane from POME is concentrated around a processing facility where technologies such as covered lagoons, digesters, flaring systems and biogas engines already exist.

Yet the technology is far from universal.

A recent review of the Earthqualizer Foundation and Inovasi Digital palm oil mill database found 2,496 mills recorded as active globally. Only 567, around 23 percent, were recorded as having a methane capture facility. More than three-quarters were recorded without one, and roughly 1,843 active mills were associated with open-lagoon treatment without methane capture. These figures reflect the current curated database rather than a complete official global census, but the pattern is difficult to ignore: methane capture remains the exception rather than the norm across a large part of the industry.

The gap is especially striking in Indonesia, where only about 11 percent of active mills in the database are recorded with methane capture, compared with substantially higher shares in Malaysia and Thailand. Public information shows that the issue has been recognized for many years. A Global Methane Initiative resource assessment published in 2015 noted that 38 methane-capture projects at Indonesian palm oil mills had been registered under the Clean Development Mechanism. That historical record shows that the technology itself is not new; what remains unresolved is how to scale it consistently across thousands of facilities.

Some individual projects show what that scaling could mean. At Sukajadi Sawit Mekar in Central Kalimantan, a UNFCCC-registered methane-recovery project estimated annual reductions of about 52,125 tonnes of CO₂ equivalent. At Pelakar Mill in Jambi, another project combining methane recovery with electricity generation estimated reductions of roughly 13,446 tonnes of CO₂ equivalent per year. These are project-specific figures rather than values that can be applied to every mill, but they demonstrate that POME methane mitigation can be substantial at facility level.

More recent research also suggests that the climate benefit can be linked with operational value. A 2026 field-scale study of POME-derived biogas used in a palm oil mill boiler reported methane-related mitigation of around 9,579 tonnes of CO₂ equivalent per year alongside a positive operating benefit from substituting part of the mill’s conventional fuel use. The broader lesson is important: methane capture does not have to be seen only as a compliance cost. In the right conditions, it can be part of a mill’s energy and resource-efficiency strategy.

This is becoming more relevant as corporate climate reporting moves deeper into the supply chain. The GHG Protocol’s Corporate Value Chain Standard was designed not simply to total Scope 3 emissions, but to help companies understand where value-chain impacts occur and where reduction efforts should be focused. Its new Land Sector and Removals Standard goes further for agricultural supply chains, providing more specific requirements for companies to account for land-related emissions and removals in their operations and value chains. The standard becomes effective in January 2027 and builds directly on the Corporate and Scope 3 Standards.

For a buyer of palm oil, this changes the meaning of Scope 3. A corporate carbon number is useful, but it tells only part of the story. What matters operationally is whether that number can be traced back to the plantations, mills and management practices that created it. Two mills processing similar volumes of fruit may have very different climate footprints depending on their sourcing, land-use history, fertilizer use, transport patterns and POME management. When those differences become visible, Scope 3 reporting starts to become a tool for deciding where action is possible rather than simply documenting what has already happened.

Article content
Methane Signals Around Palm Oil Mills With and Without Methane Capture Facilities

Satellite data may provide another piece of that picture. As an exploratory assessment, we compared 100 Indonesian mills recorded with methane capture and 100 without, using methane observations from the Copernicus Sentinel-5P TROPOMI instrument for 2025 and 2026. For each mill, atmospheric methane around the facility was compared with a wider regional background. Among observations that passed the quality filters, mills without methane capture showed a higher average methane enhancement than the group with methane capture.

The result is intriguing, but it requires caution. Sentinel-5P measures the concentration of methane in the atmospheric column, not the tonnes of methane emitted by an individual facility. The official Earth Engine documentation also notes retrieval limitations, including noise, striping and uncertainty in individual observations. TROPOMI was designed to help observe atmospheric methane patterns and support modelling of sources and sinks; it should not be treated as a direct meter attached to a palm oil mill.

Its value may instead lie in adding an independent layer of observation. A mill database may say that a methane capture system exists. Operational data may estimate how much methane should be destroyed. Satellite observations can help ask a different question: does the surrounding atmosphere show a pattern that is consistent with that expectation? If the answer is unexpected, it can guide a closer investigation rather than deliver an automatic verdict.

This is where MosaiX and Inovasi Digital see a broader role for supply-chain intelligence. Their work combines mill and supplier traceability, plantation and land-use information, GHG assessment, methane-capture facility data, transport analysis and geospatial monitoring. The aim is not to replace company primary data or engineering measurements, but to connect otherwise fragmented information so that climate reporting becomes more specific to actual suppliers and places.

In practice, that means helping companies understand which mills in their sourcing network have open lagoons, which already have methane capture, where emission estimates are highest, and where independent spatial evidence suggests further verification may be useful. It also means connecting methane with the rest of the Scope 3 picture, including land-use change, peat, fertilizer use, transport and carbon removals. The GHG Protocol itself increasingly emphasizes the importance of consistent, traceable and decision-useful information for agricultural value chains.

The challenge ahead is not only technological. Methane capture projects require capital, reliable operation, competent maintenance and a reason for the mill to keep the system functioning after installation. Buyers may benefit from lower Scope 3 emissions, while the investment has to be made upstream. Banks may see a small infrastructure project, while a consumer-goods company may see a climate target. Governments may see renewable energy, wastewater treatment or rural electricity. Each party is looking at the same pond from a different angle.

That is why collaboration matters. The most promising opportunity may be to connect these interests around real facilities: producers that can reduce emissions, buyers that need credible Scope 3 reductions, technology providers that can deliver the infrastructure, and financial institutions that can help make the economics work. Malaysia’s experience with POME biogas has already been described in the scientific literature as involving not only technology, but also public-private cooperation, financial mechanisms and institutional support.

The methane rising from a palm oil mill lagoon is invisible, but the opportunity is increasingly visible. The industry already knows the chemistry. It already has proven technologies and decades of project experience. What is still missing at scale is the connection between supply-chain data, climate accounting, investment and implementation.

For Scope 3 reporting, that may be the more important lesson. Better measurement should not simply produce a more precise footprint. It should help reveal where a tonne of emissions can actually be avoided.

The global mill and methane-capture figures and the 200-mill satellite comparison cited above are based on Inovasi Digital analysis, 2026. They are presented as supply-chain intelligence and screening results, not as an official global census or direct satellite measurement of facility-level methane emissions.

SCORE Forum 2026: Turning NDPE Commitments into Practical Supply Chain Transformation

With less than a week to go, SCORE Forum 2026 will bring palm oil industry leaders and sustainability practitioners together in Bogor to examine a question that is becoming increasingly important: what happens after supply chain risks are identified?

Bogor, Indonesia — 10 September 2026. Over the past decade, No Deforestation, No Peat and No Exploitation (NDPE) commitments have become an important foundation of responsible palm oil sourcing. Across the industry, companies have invested in sustainability policies, supplier requirements, traceability systems and satellite-based monitoring to better understand where palm oil comes from and where environmental and social risks may occur.

But identifying risk is only the beginning.

As sustainability expectations move increasingly from corporate commitments toward measurable implementation, the challenge facing the palm oil sector is changing. Companies must not only know where risks exist, but also determine what happens next: how suppliers respond, how improvements are verified, how historical problems can be addressed, and how responsible suppliers can remain connected to global markets.

This transition — from commitment to implementation, and ultimately to market access — will be at the centre of the Sustainable Commodities & Responsible Engagement (SCORE) Forum 2026, taking place on 16–17 September 2026 at ASTON Sentul Lake Resort & Conference Center in Bogor, Indonesia. The official forum theme, From Commitments to Market Access, reflects a growing recognition that sustainability is becoming closely connected to supply chain resilience, competitiveness and access to international markets.

Convened by Earthqualizer and Inovasi Digital, SCORE Forum is designed as a working platform for actors across the palm oil value chain. Growers, processors, traders, consumer-goods companies, financial institutions, policymakers, technology providers and sustainability practitioners will come together to explore practical approaches to responsible sourcing and supply chain transformation.

A central question running through the Forum is deceptively simple: What can companies and suppliers practically do once a sustainability risk has been identified?

For years, much of the sustainability conversation has understandably focused on detecting deforestation, mapping supply chains and identifying non-compliance. These systems remain essential. Yet monitoring alone does not restore forests, improve supplier practices or strengthen smallholder livelihoods. Nor does simply removing a supplier from one supply chain necessarily resolve the underlying environmental or social problem.

The next stage of NDPE implementation therefore requires greater attention to supplier engagement, corrective action, recovery and responsible re-entry. The objective is not to weaken sustainability standards, but to create credible mechanisms through which suppliers can stop non-compliant practices, address past impacts, demonstrate measurable improvement and rebuild access to responsible markets.

That discussion is becoming even more relevant as regulatory and market expectations evolve. Traceability, geolocation, deforestation monitoring and evidence-based due diligence are increasingly becoming part of the infrastructure required for market access. At SCORE Forum, sessions will examine responsible supply chains, traceability and monitoring, forest protection and restoration, as well as the implications of changing governance and market requirements.

The programme will combine plenary discussions, moderated panels, technical workshops, multi-stakeholder dialogue and practical Industry Clinics. Topics include NDPE performance, EUDR readiness, traceability systems, ESG reporting and access to financing, creating an opportunity to connect sustainability ambition with the operational and financial realities faced by companies and suppliers.


The Forum will also bring together perspectives from across the regional and international palm oil sector. Confirmed speakers include representatives from Roundtable on Sustainable Palm Oil (RSPO), PT Danantara Sumberdaya Indonesia (DSI), the Malaysian Palm Oil Board (MPOB), the Council of Palm Oil Producing Countries(CPOC),  Unilever, Musimmas, Wilmar, Apical, SD Guthrie, Fuji Oil, Bumitama and other organisations spanning production, processing, markets and sustainability.

Within this wider ecosystem, MosaiX contributes a supply-chain intelligence and technology perspective to the transformation challenge. Its work connects traceability and supplier intelligence with deforestation and land-conversion monitoring, NDPE risk assessment and recovery, climate and nature risk intelligence, and smallholder and landscape-level interventions.

The value of these systems increasingly lies not simply in producing another risk map or dashboard, but in connecting information with decisions. A deforestation alert needs to lead to supplier engagement. A traceability gap needs to trigger data improvement. A historical liability needs a credible recovery process. Climate or biodiversity risks need to inform investment and sourcing decisions. And smallholders need pathways that allow them to participate in responsible markets rather than becoming unintended casualties of increasingly complex compliance requirements.

This is where collaboration becomes critical.

No single company, monitoring platform, certification system, financial institution or government agency can transform a commodity supply chain alone. Environmental risks often extend beyond concession boundaries, while suppliers can serve multiple buyers and smallholders frequently operate through complex networks of dealers, mills and intermediaries. Solutions therefore have to work across companies and across landscapes.

SCORE Forum 2026 aims to create space for precisely that conversation: moving beyond the question of who has a sustainability commitment toward the more difficult questions of how those commitments are implemented, how progress is demonstrated, and how transformation can be sustained commercially over time.

Ultimately, the future of responsible palm oil may depend less on adding another commitment and more on making existing commitments work — connecting data with action, risk with recovery, and sustainability performance with continued market access.

On 16–17 September in Bogor, SCORE Forum will bring those conversations into the same room.

SCORE Forum 2026 — From Commitments to Market Access
16–17 September 2026 | ASTON Sentul Lake Resort & Conference Center, Bogor, Indonesia

Learn more and register for SCORE Forum 2026